

UNest: Invest & Save for Kids

- 430.00 Reviews
- 3.8
- Downloads
- 100,000+
Our take on UNest: Invest & Save for Kids from Appgk
Saving for a child sounds simple until everyday life gets in the way. There are school expenses, birthdays, changing priorities, and the usual temptation to postpone long-term planning. I found UNest: Invest & Save for Kids most useful as a focused way to turn that intention into a repeatable habit. It is a finance app from UNest Holdings, Inc. built around a UTMA custodial account, so the central idea is not merely putting money aside but investing it for a child’s future.
That focus makes the experience different from a regular savings app. I am not opening it to manage every part of my personal budget or to replace a bank account. I am opening it to check a child-focused financial goal, add money, and keep the long view visible. The app is free to download, although it includes in-app purchases ranging from around five dollars to around one hundred fifty dollars per item. That pricing detail matters because the free entry point does not automatically mean every part of the experience costs nothing.
How connectivity shapes the UNest experience
The app’s usefulness depends on being able to reach current account information and complete financial actions through a live connection. In practice, that means I treat it as an online finance tool rather than something to browse casually in airplane mode. A weak signal can turn a simple check into an uncertain moment: a balance may take longer to appear, a contribution may need extra patience, and repeatedly tapping a button is a bad idea when money is involved.
That network dependence is not a minor detail in a finance app. When I use a children’s investing service, I want to know whether an action has actually gone through before trying it again. If the screen pauses after I submit something, I would first check for a confirmation or transaction history rather than immediately repeating the action. This is one of the most important habits to develop with UNest: never treat a loading pause as proof that a financial action failed.
Best Parts of UNest: Invest & Save for Kids
Things to Keep in Mind About UNest: Invest & Save for Kids
The connection also affects how I plan my sessions. I prefer opening the app at home or somewhere with a reliable mobile signal, especially when reviewing account details or making a contribution. A quick glance while walking through a crowded station is fine only if I am reading information. For anything that changes the account, I would wait until the connection is stable and I have enough time to verify the result.
What happens during ordinary network-dependent moments
A common use case is a parent receiving money for a child’s birthday and deciding to invest part of it instead of letting it disappear into everyday spending. The useful workflow is to open the account, review the destination of the money, make the contribution, and then confirm that the app reflects the action. That sequence sounds obvious, but it prevents a surprisingly common mistake: assuming that starting a transfer and completing it are the same thing.
News and Features Related to UNest: Invest & Save for Kids

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
Another realistic situation is a grandparent asking how the child’s account is progressing. UNest can serve as a conversation starter because the purpose of the account is easy to explain: money is being set aside in a custodial investment account for the child. I would still avoid opening the app in a rushed public setting just to answer a question immediately. Financial information deserves the same care as a banking app, even when the interface feels approachable.
The mobile format is particularly helpful for small decisions. If I remember a contribution while waiting for an appointment, I can use that moment to review my plan rather than relying on memory. However, the convenience can also encourage impulsive actions. A child-focused investment goal works best when contributions fit a household budget, not when the app makes adding money feel like a spontaneous purchase.
Don't want to read the full review?
Using it across different mobile contexts
UNest is well suited to parents who manage most of their finances from a phone. The app is available for devices running Android 7.0 or later, which covers many older phones, but the practical experience still depends on the device, its connection, and whether the operating system is kept in a usable condition. I would check compatibility before planning to use an older spare phone as the main device.
On a small screen, the most useful approach is to separate checking from decision-making. I might open the app during a short break to see whether the account is on track, but I would save questions about contributions, custodial ownership, and long-term expectations for a calmer session. This distinction keeps mobile convenience from replacing proper financial thinking.
Screenshots
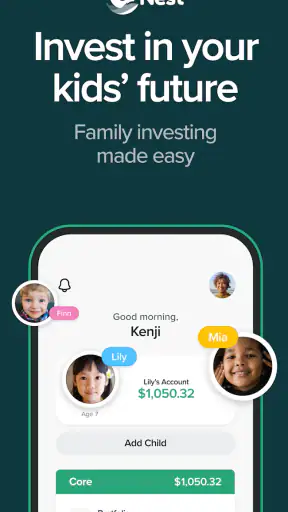
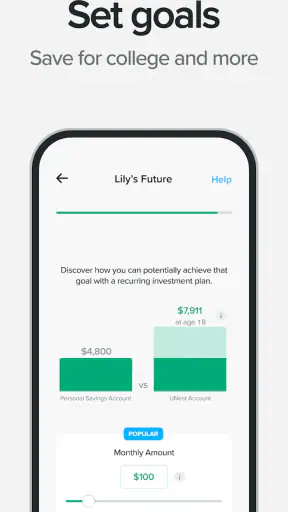
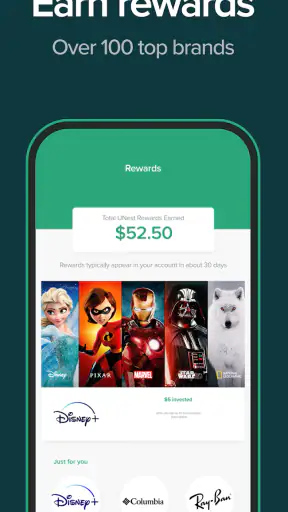
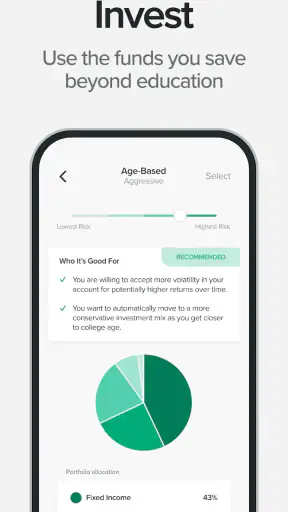
The app also makes sense for households where more than one adult contributes to a child’s future, but that arrangement requires clear communication outside the app. Before adding money, everyone involved should agree on the purpose of the account and who is responsible for monitoring it. A mobile interface cannot resolve confusion between parents, relatives, or other contributors. The custodial structure is important, so I would make sure every adult understands that this is not simply a flexible personal savings pocket.
For a parent who wants a complete budgeting system, UNest is likely too narrow. A bank app may be better for checking bills, moving money between everyday accounts, and handling routine cash management. A broad investment platform may offer more control for someone who wants to choose and manage investments personally. UNest’s appeal is the child-specific focus, not the promise of replacing those other tools.
Recovering from weak connections and interrupted sessions
Financial apps should be used with a recovery plan, and my approach with UNest is deliberately cautious. If the app stops responding, I close the possibility of duplicate actions first: I do not press the contribution control several times, and I do not assume that leaving the screen means nothing happened. I reconnect, reopen the app, and look for the updated account state or confirmation before doing anything else.
This matters especially when using mobile data in a place where the signal moves between networks. A brief interruption can happen while an action is being processed, leaving the user unsure whether to wait or retry. The safest response is to pause, make a note of what I attempted, and verify the account once the connection is dependable. If the result remains unclear, contacting the appropriate support channel is better than experimenting with another submission.
I also recommend keeping account-related notifications and messages easy to find, without assuming that a notification alone is a complete record. The app itself should be the place where I verify the account state. A screenshot can help me remember what I saw, but it should not replace checking the current information after reconnecting.
Recovery is not only about internet access. It also includes changing phones, updating the operating system, or returning to the app after a long break. Before switching devices, I would make sure I can still access the account through the normal sign-in process and that important account details are available. This is a sensible precaution for any financial service, and it becomes more important when the goal is long term and the child may not use the account for years.
Keeping mobile data use sensible
UNest is not the kind of app I would expect to consume data continuously. Most users will probably open it for short account checks or occasional contributions rather than leave it running. Even so, I prefer using Wi-Fi for larger updates or account setup and reserving mobile data for quick reviews. That approach is less about a precise data saving promise and more about avoiding unnecessary uncertainty while handling financial information.
Data-conscious use also means resisting repeated refreshes. If the balance does not update immediately, refreshing again and again may not solve the underlying connection problem. I would wait, move to a stronger signal, and then check once more. This is a small habit, but it reduces frustration and makes it easier to tell whether a change is genuinely reflected.
There is a privacy angle as well. I would avoid reviewing a child’s financial account on unsecured public networks when I can wait for a trusted connection. I would also avoid discussing account details aloud in crowded places. The app’s friendly purpose should not make me treat it like a casual social application; it still handles sensitive financial information.
What the app does well for a child-focused goal
The strongest part of UNest is its narrow purpose. Instead of asking me to build a complicated investment routine from scratch, it frames the task around a child and a custodial account. That framing can make long-term saving feel more concrete. A parent who has repeatedly meant to start investing for a child may find it easier to act when the app keeps the goal in one dedicated place.
I also like the psychological value of separating this goal from everyday spending. Money in a general checking account is easy to mentally reassign to groceries, repairs, or entertainment. A dedicated child-focused account creates a clearer boundary. That does not guarantee good returns or remove investment risk, but it can improve discipline by making the purpose visible.
The app’s audience is reflected in its Everyone content rating, which makes the product broadly accessible from a store-rating perspective. Still, I would not interpret that as a reason to hand financial decisions to a child without supervision. The account is for a child’s benefit, while the custodial responsibility belongs with the adult managing it. Parents should explain the goal in age-appropriate language and keep control of decisions that require adult judgment.
UNest has also built a substantial user footprint, with over one hundred thousand installs and an average rating of around 3.8 from roughly two and a half thousand ratings. I read that as evidence of real interest rather than a guarantee that every family will enjoy the experience. The rating suggests a mixed but generally workable reception, so I would approach it as a practical tool with trade-offs rather than a flawless financial solution.
Where the experience needs careful judgment
The biggest limitation is that a simple interface cannot simplify the underlying financial responsibility. A custodial investment account has rules and consequences that deserve attention before money is added. I would want to understand who controls the account, how the child’s future access works, and how contributions fit into the family’s wider financial plan. The app can organize the action, but it should not be treated as a substitute for understanding the account structure.
Cost also deserves a close look. The app itself is free, but the presence of in-app purchases from around five dollars to around one hundred fifty dollars per item means I would review any paid option carefully before confirming it. I would not assume that a paid feature is necessary for the basic goal, and I would compare its value with simply making a regular contribution. Parents should also distinguish between an app purchase and money invested in the child’s account; they are not the same kind of financial decision.
Another trade-off is control. Someone who wants to select individual investments, adjust a detailed portfolio, or study advanced market tools may find the child-centered approach restrictive. In that case, a conventional brokerage account or a more comprehensive investment service may be a better match. On the other hand, too much control can become a barrier for a beginner who never gets around to starting. UNest is more compelling when simplicity helps a family follow through.
I would also skip it if the household has no emergency cushion and is using the app to avoid dealing with immediate financial pressure. Long-term investing for a child is meaningful, but it should not come before essential bills or high-priority debt. The right tool cannot compensate for an unsuitable financial order of operations.
How I would build a reliable routine
My preferred routine would begin with a clear purpose: education, a future milestone, or simply giving the child a financial head start. I would decide what amount is genuinely comfortable, then schedule my own reminder to review the account periodically. The point is consistency, not checking the screen every day. Frequent monitoring can create emotional reactions to normal market movement, while a long-term goal benefits from patience.
I would use a stable connection for setup and contributions, verify each completed action, and record the reason for any unusual deposit. If relatives contribute, I would explain the account’s purpose beforehand so that gifts do not become confusing requests or duplicated transfers. This workflow is more valuable than simply downloading the app because it turns the service into part of a household plan.
It is also worth deciding what the app should not do in the family routine. I would not use it as a general spending wallet, a replacement for emergency savings, or a daily market-watching tool. Keeping those boundaries clear protects the child-focused purpose and reduces the chance of making a long-term decision based on a short-term mood.
The current version is 3.8.1, so I would keep the app updated through the normal device store process and avoid delaying updates indefinitely. Updates can affect compatibility and reliability, particularly on older phones. At the same time, I would not update immediately before an important contribution if I could choose otherwise; I prefer giving myself time to confirm that the app opens and the account is accessible afterward.
My connectivity verdict
UNest works best when I view it as a focused, online companion for a child’s investment goal rather than as a complete financial command center. Its mobile design makes occasional contributions and account reviews convenient, but that convenience depends on a dependable connection and careful verification. The app is most comfortable in a calm, connected setting, not during a rushed moment with an unstable signal.
I would recommend it to a parent who wants a dedicated UTMA custodial account experience, prefers a guided child-focused approach, and values a straightforward routine over detailed investment control. I would be more cautious for someone comparing every fee, demanding advanced portfolio tools, or needing a full budgeting and banking system in one place. Those users may be happier with a bank or brokerage service designed for broader control.
After using it, my view is positive but measured. The free starting point and clear child-centered purpose lower the barrier to beginning, while the in-app purchase range and custodial responsibilities mean I would read each screen carefully before committing money. With a stable connection, a deliberate contribution habit, and realistic expectations about what the app can and cannot manage, it can be a useful part of a family’s long-term plan. Its real strength is not making investing effortless; it is making one important family goal easier to keep visible.
UNest: Invest & Save for Kids FAQ
What is UNest: Invest & Save for Kids?
UNest is a family-focused investing and savings app designed to help parents and relatives build money for a child’s future. It generally uses an investment account intended for minors, allowing adults to contribute regularly or make one-time deposits. The app presents the process in a simplified way, so users can track contributions and investment progress without needing advanced investing experience.
How does investing through UNest work?
After creating an account and providing the required personal and child-related information, you choose how much to contribute and select from the investment options available in the app. UNest handles the portfolio process, while the value of investments can rise or fall with the market. Contributions are not guaranteed to grow, so users should review the risks, fees, and account terms before investing.
Who can open a UNest account and contribute money?
UNest is primarily aimed at parents and guardians who want to invest for a child, although eligible family members or friends may also be able to contribute through supported gifting features. Availability and account eligibility can depend on factors such as residency, age, identity verification, and applicable financial regulations. Check the current requirements in the app before starting the registration process.
Are there fees or minimum contributions on UNest?
UNest may charge account or management fees, and the exact pricing can depend on the plan, account type, and current terms shown during signup. Some features may require a subscription or recurring payment, while contribution minimums can vary. Before confirming an account, carefully review the fee schedule, transfer conditions, and any costs associated with withdrawals or additional services.
Can money invested with UNest be withdrawn whenever I want?
Access to funds depends on the type of account opened and the legal rules governing investments for minors. In some arrangements, withdrawals may be limited, require approval, or need to benefit the child rather than the contributing adult. Investment sales can also take time to settle, and market losses are possible. Read UNest’s withdrawal, tax, and account ownership policies before depositing money.











